by Katherine Soditus | Jan 12, 2026 | Uncategorized
Refinancing a home loan can be a powerful tool for homeowners, but it’s not always the right choice. The decision depends on your financial goals, current mortgage terms, and market conditions. Understanding when refinancing makes sense can help you save money, reduce stress, and achieve long-term financial stability.
Lower Your Interest Rate
One of the main reasons homeowners refinance is to secure a lower interest rate. Even a small reduction can significantly reduce monthly payments and total interest over the life of the loan. Refinancing is most beneficial when current rates are substantially lower than your existing mortgage rate.
Shorten Your Loan Term
Refinancing to a shorter-term mortgage, such as switching from a 30-year to a 15-year loan, allows you to pay off your home faster and save on interest. Monthly payments may increase, but the long-term savings can be substantial.
Switch from an Adjustable-Rate to a Fixed-Rate Mortgage
If you currently have an adjustable-rate mortgage (ARM), refinancing to a fixed-rate mortgage can provide stability. Fixed rates protect you from potential future rate increases, making budgeting easier and offering peace of mind.
Access Home Equity
Cash-out refinancing allows homeowners to tap into home equity for major expenses like home improvements, education, or debt consolidation. It’s important to weigh the benefits against the risks, as increasing your loan balance can lead to higher monthly payments.
Consider the Costs
Refinancing isn’t free. Closing costs, appraisal fees, and other expenses can add up. It typically takes a few years to recoup these costs through monthly savings. Make sure your financial situation and long-term plans align with refinancing before moving forward.
Conclusion
Refinancing your home loan makes sense when it lowers your interest rate, shortens your loan term, switches you to a more stable mortgage, or allows you to access home equity strategically. By carefully evaluating your goals, current rates, and costs, you can make a refinancing decision that strengthens your financial future.
by Katherine Soditus | Jan 8, 2026 | Uncategorized
Your home isn’t just a place to live, it’s one of your biggest financial assets. Building equity means increasing the portion of your home you truly own, and it can open doors to future opportunities like refinancing, home improvements, or even buying another property. Here’s how to grow your equity over time and why it matters.
What Is Home Equity?
Equity is the difference between your home’s market value and what you owe on your mortgage. For example, if your home is worth $400,000 and you owe $250,000, your equity is $150,000. The more equity you have, the stronger your financial position.
5 Smart Ways to Build Equity
1) Make Extra Mortgage Payments
Even small additional payments can make a big difference. Paying a little extra toward your principal each month reduces your balance faster and saves on interest.
Pro tip: Round up your payment or make one extra payment per year. It adds up over time. If you get a bonus or tax refund, consider applying part of it to your mortgage.
2) Avoid Frequent Refinancing
Refinancing can be smart when rates drop, but doing it too often resets your payoff timeline. Make sure the savings outweigh the costs before you refinance.
Rule of thumb: If you can lower your rate by at least 0.75% and plan to stay in the home long enough to recoup closing costs, refinancing may make sense.
3) Maintain Your Home
Regular upkeep protects your property value. Fix leaks, service your HVAC, and keep your roof in good shape. A well-maintained home holds its value and attracts buyers when it’s time to sell.
Tip: Create a seasonal maintenance checklist, spring for gutters and landscaping, fall for sealing windows and servicing heating systems.
4) Choose Upgrades Wisely
Not all renovations pay off equally. Kitchens and bathrooms typically offer the best return. Energy-efficient upgrades like smart thermostats, better insulation, and high-performance windows can also boost value and lower bills.
Budget-friendly ideas: Fresh paint, updated lighting, and modern hardware can make a big impact without draining your wallet.
5) Stay Put
The longer you own your home, the more equity you build. Real estate tends to appreciate over time, so patience pays off.
Tip: If you’re considering selling, weigh the benefits of waiting another year or two for more growth, especially if your local market is trending upward.
Why Equity Matters
Equity gives you financial flexibility. You can tap into it for home improvements, consolidate debt, or fund major life goals. Home equity is also a safety net. The more equity means more options if the market shifts.
Example: A home equity line of credit (HELOC) can provide funds for renovations or emergencies at lower interest rates than credit cards.
Common Mistakes to Avoid
-
Over-improving: Spending $50,000 on a luxury kitchen in a $250,000 neighborhood may not pay off.
-
Ignoring maintenance: Small issues like leaks or cracked caulk can lead to big repairs later.
-
Skipping research before refinancing: Closing costs can eat up savings if you don’t plan carefully.
Helpful Resources
-
bankrate.com — Mortgage calculators and refinancing tips
-
zillow.com — Home value estimates and market trends
-
energystar.gov — Energy-efficient upgrade ideas
-
familyhandyman.com — DIY maintenance guides
Bottom Line
Building equity isn’t complicated; it’s about smart payments, good maintenance, and strategic upgrades. Treat your home like an investment, and it will reward you over time. Whether you’re planning to stay for decades or sell in a few years, these steps will help you maximize value and financial security.
by Katherine Soditus | Dec 11, 2025 | Uncategorized
The holiday season is all about spending time with family and friends, but if you live in a smaller home or apartment, hosting can feel overwhelming. The good news? With a little creativity and planning, you can create a warm, festive atmosphere without feeling cramped. Here are practical tips to make your holiday gatherings enjoyable, even in limited space.
1. Declutter Before You Decorate
Before you bring out the holiday décor, take time to clear unnecessary items. Removing extra furniture, unused chairs, and clutter from countertops instantly opens up your space. A clean, streamlined environment makes your home feel larger and more inviting.
2. Choose Space-Saving Decorations
Oversized decorations can make a small space feel even smaller. Instead, opt for:
-
Slim or tabletop trees instead of full-size versions.
-
Vertical décor like wall-mounted wreaths or garlands.
-
String lights to add warmth without taking up floor space.
These choices keep the festive spirit alive without sacrificing room for guests.
3. Rearrange Furniture for Flow
Think about how people will move through your home. Push larger pieces like sofas against the wall and remove any unnecessary tables. If you have a dining table, consider using benches or folding chairs that can be tucked away when not in use. Creating open pathways helps guests feel comfortable and prevents congestion.
4. Create Multiple Serving Stations
Instead of crowding everything onto one table, spread out food and drinks. Use a kitchen counter for appetizers, a side table for desserts, and a bar cart for beverages. This encourages guests to move around and prevents everyone from gathering in one spot.
5. Keep the Menu Simple
A smaller space often means limited kitchen capacity. Choose dishes that can be prepared ahead of time or served buffet-style. Finger foods and one-pot meals are excellent options because they minimize the need for extra serving dishes and utensils.
6. Use Vertical Space for Storage
If you’re short on surface space, think upward. Shelves, wall hooks, and hanging racks can hold coats, bags, and even extra serving trays. This keeps floors clear and makes the space feel organized.
7. Set the Mood with Lighting and Music
Soft lighting and background music can make a small space feel cozy rather than cramped. Use candles, string lights, or dimmable lamps to create a warm glow. A curated playlist adds to the festive atmosphere without overwhelming conversation.
8. Limit the Guest List
It’s tempting to invite everyone, but a smaller space calls for a more intimate gathering. Focus on quality time with a few close friends or family members. This ensures everyone has room to relax and enjoy themselves.
Bottom Line
Hosting holiday gatherings in a small space is all about smart planning and creative solutions. By decluttering, choosing space-saving décor, and organizing your layout, you can create a warm, welcoming environment that feels festive and comfortable. Remember, the holidays are about connection—not square footage.
Thinking About More Space Next Year?
If hosting in a small home has you dreaming of a bigger one, let’s talk! I can help you explore options that fit your lifestyle and budget.
:telephone_receiver: Call me today or send a message to start planning for the new year.
by Katherine Soditus | Nov 10, 2025 | Uncategorized
Real estate has long been one of the most effective ways to build wealth. Unlike many other investments, property allows you to use leverage, which means using borrowed money to increase your potential returns. When used wisely, leverage can help you grow your real estate portfolio faster and build long-term financial security.
Here’s how successful investors use mortgages as a powerful tool to maximize their wealth.
:chart_with_upwards_trend: What Is Leverage in Real Estate?
Leverage in real estate means using borrowed funds, such as a mortgage, to buy a property instead of paying the full price up front. This allows you to control a valuable asset while investing only a portion of your own money.
For example:
If you buy a $400,000 property with a 20% down payment, you invest $80,000 of your own funds. The remaining $320,000 is financed through a mortgage. If the property’s value rises to $440,000, you have earned a $40,000 gain on your $80,000 investment, or a 50% return.
That increase is the power of leverage at work.
:bank: Why Mortgages Are Key to Wealth Building
Mortgages make it possible for investors to grow their portfolios without waiting years to save enough cash to buy properties outright. Instead, you can purchase multiple assets that appreciate over time and generate income.
Here are a few reasons why leveraging through mortgages is so effective:
-
Capital efficiency: You keep more cash available for other investments or emergencies.
-
Scalability: You can purchase more than one property and diversify your income streams.
-
Wealth growth: Property values and rental income can rise while your mortgage balance decreases through regular payments.
When done strategically, this creates a compounding effect where both appreciation and cash flow work together to build wealth.
:moneybag: How Smart Investors Use Leverage Strategically
Leverage can be powerful, but it requires careful planning. Here are key strategies that experienced investors use:
1. Start with a Manageable Down Payment
Many investors begin with a 20% down payment to avoid private mortgage insurance (PMI). This allows them to secure financing while maintaining a healthy balance between risk and reward.
2. Choose Properties with Positive Cash Flow
A property should ideally generate more rental income than it costs to own and maintain. Positive cash flow ensures that the property pays for itself while also reducing your mortgage balance over time.
3. Use Equity to Buy More Properties
As your property appreciates and your loan balance decreases, you build equity. You can refinance or use a home equity line of credit (HELOC) to access that equity and invest in another property. This allows your portfolio to grow without needing large amounts of new capital.
4. Take Advantage of Low Interest Rates
Locking in a low fixed-rate mortgage allows you to control your costs while your property value and rents potentially increase. This widens your profit margin and strengthens long-term returns.
:bar_chart: The Risk Side of Leverage
Leverage can amplify gains, but it can also magnify losses if not used responsibly. It is important to understand the risks before taking on multiple mortgages.
-
Market fluctuations: Property values can drop, reducing equity.
-
Vacancy risks: Rental income may not always cover mortgage payments.
-
Interest rate changes: Adjustable-rate loans can increase in cost over time.
To manage these risks, keep a financial cushion, choose quality properties in stable markets, and avoid overextending your borrowing capacity.
:brain: The Mindset of a Smart Investor
Successful investors treat leverage as a tool, not a shortcut. They understand that mortgages are a way to control more assets while maintaining discipline and a long-term perspective.
They focus on:
By thinking strategically and making data-driven decisions, investors can use leverage to create financial independence over time.
:sparkles: Final Thoughts
The power of leverage lies in its ability to multiply your investment potential. By using mortgages wisely, investors can control more assets, build equity, and create consistent income that grows with time.
However, leverage should be approached with caution and strategy. The most successful investors balance opportunity with risk, allowing their properties to work for them while maintaining financial stability.
When used correctly, leverage can transform real estate from a single investment into a powerful engine for long-term wealth creation.
by Katherine Soditus | Oct 14, 2025 | Uncategorized
October is the perfect time to talk about things that go bump in the night, and in the real estate world, that often means myths and misconceptions that haunt buyers, sellers, and investors alike. As a seasoned real estate agent, I’ve heard it all: tales of cursed properties, impossible financing, and market monsters that scare people away from making smart moves. So let’s shine a light on some of the spookiest real estate myths and set the record straight.
Myth #1: You Need 20% Down to Buy a Home
This is one of the most persistent myths out there. While putting 20% down can help you avoid private mortgage insurance (PMI), it’s not a requirement. Many loan programs allow buyers to put down as little as 3% and some even offer zero-down options for qualified applicants. First-time buyers, veterans, and rural homebuyers often have access to flexible financing. Don’t let this myth scare you away from exploring your options.
Myth #2: The Market Is Too Volatile to Invest Right Now
Real estate markets do fluctuate, but that doesn’t mean it’s always a bad time to invest. In fact, savvy investors know that opportunities often arise during periods of uncertainty. Whether it’s buying undervalued properties, flipping homes, or securing long-term rentals, some strategies work in every market cycle. The key is to understand your goals and work with a knowledgeable agent who can help you navigate the terrain.
Myth #3: Haunted Houses Are Impossible to Sell
Believe it or not, some buyers are actually drawn to homes with a spooky reputation. While disclosures about deaths or paranormal activity vary by state, most buyers are more concerned with the condition, location, and price of a property than its ghost stories. If a home has a history that makes you uneasy, it’s worth discussing with your agent—but don’t assume it’s unsellable.
Myth #4: You Should Always Wait for Spring to Buy or Sell
Spring is traditionally a busy season in real estate, but that doesn’t mean it’s the only time to make a move. Fall and winter can offer unique advantages: less competition, more motivated sellers, and faster closings. For investors, off-season purchases can mean better deals. For sellers, listing in October or November can attract serious buyers who are ready to act before the holidays.
Myth #5: All Real Estate Agents Are the Same
This one gives me chills. The truth is, your choice of agent can make or break your experience. A skilled, ethical, and experienced agent will advocate for your interests, negotiate effectively, and guide you through every step of the process. Don’t settle for someone who merely opens doors; instead, look for someone who brings valuable insight, effective strategy, and professionalism to the table.
Real estate doesn’t have to be scary. Whether you’re buying your first home, selling a property, or investing in your portfolio, separating fact from fiction is essential. If you’ve heard a rumor or myth that’s making you hesitate, let’s talk about it. I’m here to help you make informed decisions and avoid the tricks while finding the treats in today’s market.
by Katherine Soditus | Apr 7, 2025 | Residential | Pending

$169,000
Pending
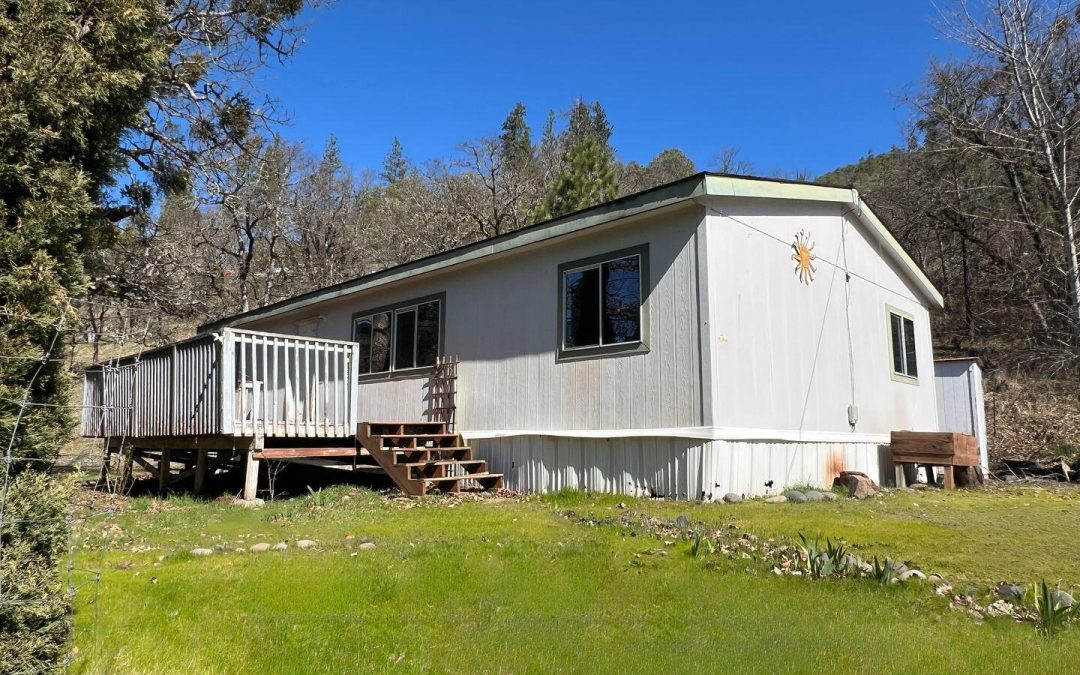
WOW Factor! Almost an acre in Shady Cove with a cozy 3bd/2ba home. Open floor plan, dining area, great storage, roomy bedrooms with privacy floor plan – and country views! Carport with room for RV, meter at pole. Adorable garden enclaves – roses, Lemon Balm, Daffodils, garden paths, oversized deck – it’s adorable! Shared well; walking distance to downtown area and Rogue River. This property has been placed in an upcoming event. All bids should be submitted at xomeDOTcom/auctions (void where prohibited). Please submit any pre-auction offer received through the property details page on XomeDOTcom. Any post-auction offers will need to be submitted directly to the listing agent. All offers will be reviewed and responded to within 3 business days. All properties are subject to a 5% buyer’s premium pursuant to the Auction Participation Agreement and Terms & Conditions (minimums will apply). Please contact listing agent for details and what is paid on this property.
by Katherine Soditus | Apr 1, 2025 | Residential | Closed

$835,000
Closed
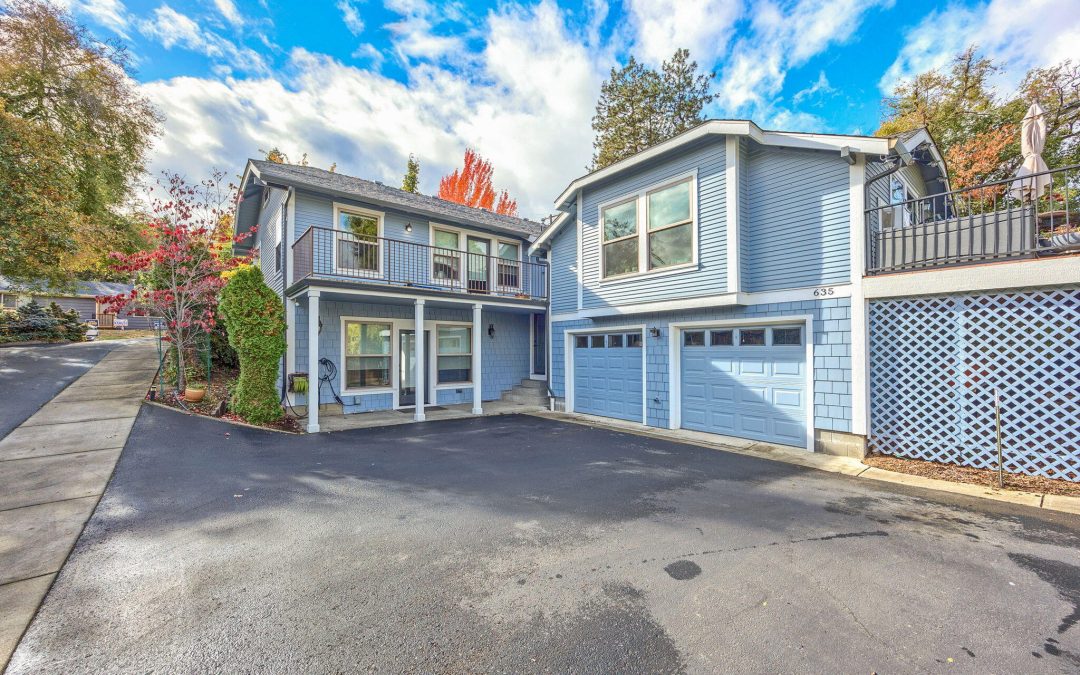
This charming craftsman was remodeled down to the studs in 2008 and blends modern comforts with classic style, plus a legal studio ADU above the 2 car garage offers a perfect place for guests or rental income. Ideally located close to downtown & trails, the property offers views of Grizzly Peak without steep access. The main level is well appointed with hardwood floors throughout, cozy living room with gas fireplace, eating area, chic kitchen with stainless steel appliances & granite countertops, 2 bedrooms with deck access and full bathroom. The lower level provides an additional bedroom/office, laundry room and spacious primary suite with exterior access and kitchenette. This versatile floor plan provides options for a multi-generational living, home business/office space and investment opportunity. Plus it has lots of storage, central vacuum, and EV charger. Come see this quality home in a lovely neighborhood today!
by Katherine Soditus | Mar 31, 2025 | For Buyers, Sellers
As the weather warms up, the spring housing market kicks into high gear, creating an exciting opportunity for both homebuyers and sellers. If you’re considering buying or selling a home this season, it’s essential to understand the key trends that define the spring market. In this article, we’ll explore what you can expect from the spring housing market and how to make the most of these changes.
1. Increased Inventory in the Spring Housing Market
Spring is one of the best times to buy a home, thanks to the increase in inventory. More homeowners choose to list their properties as the weather improves, gardens bloom, and families prepare to move before the new school year begins. This boost in available homes offers buyers a wider selection, making it easier to find your dream home. For sellers, this is the perfect opportunity to capitalize on the increased demand. However, with more competition, it’s important for sellers to price their homes competitively and for buyers to act quickly.
Pro Tip: Buyers should start their home search early in spring to have the best selection of homes. Sellers, on the other hand, should prepare their homes to stand out in a crowded market.
2. Rising Home Prices in Spring
One of the key trends in the spring housing market is rising home prices. With more buyers entering the market and limited inventory in some areas, demand often outweighs supply, leading to higher prices. Multiple offer situations become more common, driving up the final sale price. If you’re a seller, spring is an excellent time to list your home for a potential price increase. Buyers, however, may need to adjust their expectations and be prepared for competitive pricing in desirable neighborhoods.
Tip for Buyers: Work with a real estate agent to identify pricing trends in your area and be ready to negotiate if the asking price is higher than expected.
3. More Competition Among Homebuyers
Spring is the season when most buyers begin their home search. Whether it’s because they want to move before the summer or need to settle before the school year starts, more buyers flock to the market. This increased competition can lead to bidding wars for popular homes. As a buyer, this means you’ll need to act fast, make competitive offers, and possibly even bid above the asking price. For sellers, it’s a prime time to take advantage of this surge in demand.
Buyer Tip: To stand out in a competitive market, get pre-approved for a mortgage and be ready to make a strong offer when you find the right home.
4. Potential for Favorable Mortgage Interest Rates
While mortgage rates can fluctuate, spring is often a time when interest rates remain relatively low compared to historical averages. If you’re a buyer, this could mean lower monthly payments and more purchasing power. However, it’s important to monitor the market, as the Federal Reserve could raise interest rates, impacting your mortgage rate. If you lock in a favorable rate early, you could save a significant amount of money over the life of your loan.
Tip for Buyers: Shop around for the best mortgage rates and consider locking in a rate if you find one that suits your budget. Even a small difference in interest rates can make a big impact on your long-term payments.
Conclusion
The spring housing market is one of the most active times of the year, and it comes with key trends that buyers and sellers should be prepared for. From increased inventory and rising prices to more competition and potentially favorable interest rates, understanding what to expect can help you navigate the market successfully. Whether you’re looking to buy or sell, this spring could be the perfect time to make a move in the real estate market. Stay informed, plan ahead, and work with a trusted real estate professional to make the most of this dynamic season.
by Katherine Soditus | Mar 29, 2025 | Residential | Active

$269,000
Active
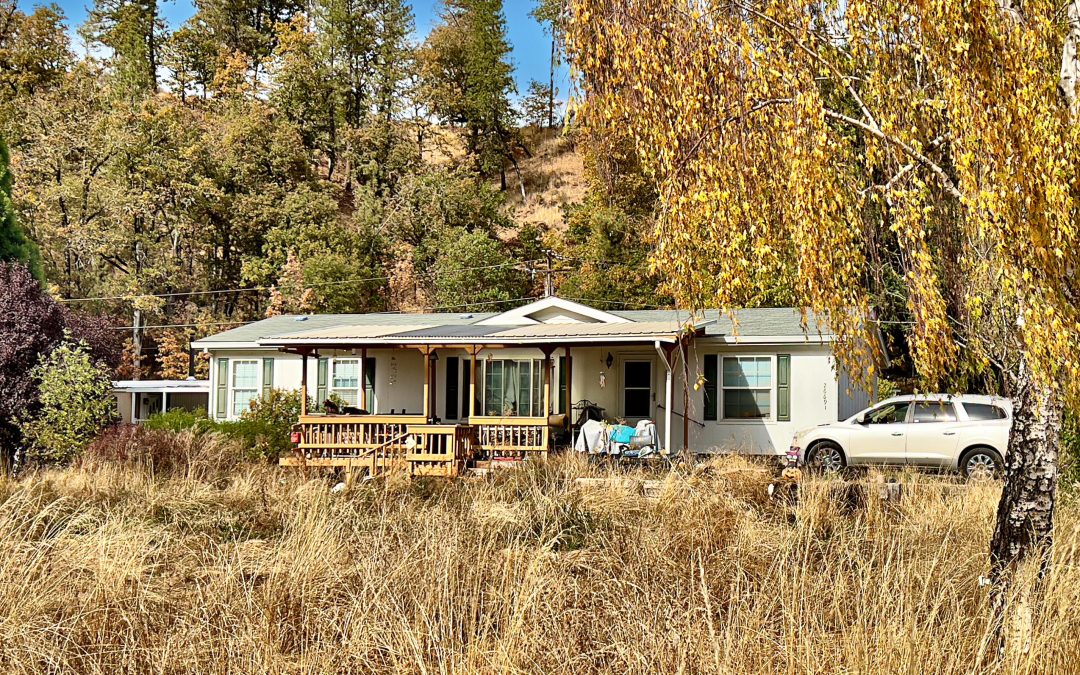
ACREAGE, ”SHOP” w/ADU POTENTIAL, CARPORT w/RV METER, WOW! Spacious 3bd/2ba manufactured home with covered porch on mostly level acreage. Split floor plan offers a primary suite with oversized soaking tub, dual vanities and a separate shower. Vaulted living spaces with ceiling fans; laundry room/mudroom. The wood framed workshop with glass slider may potentially convert to an ADU or additional finished area (inquire with county; workshop was remodeled from a previous ”old house”) The upper detached metal carport has an RV meter and the lower carport is adjacent to a shed; there’s ample room for storage and plenty of parking for RV, boat, trailers & toys. Property features multiple sheds/storage outbuildings, a fire-pit, even an older hot tub. Property is partially fenced. New 2000 gallon holding tank and pump just installed 10/2021, new well pump & pipeline in 2022. This home has ”short sale conditions” and is subject to bank approval; inquire with listing agent for details.
by Katherine Soditus | Mar 24, 2025 | Sellers
In today’s competitive real estate market, sellers are seeking ways to stand out and sell quickly. One effective strategy is a pre-listing inspection. While it may seem like an added expense, a pre-listing inspection offers several benefits that can help you sell faster and at a better price. Here’s why it could be worth considering.
What is a Pre-Listing Inspection?
A pre-listing inspection is a home inspection done before your property hits the market. A certified inspector checks the condition of the home and identifies any issues that may need fixing. This report can guide your decisions and help you price your home accurately.
Key Benefits of a Pre-Listing Inspection
1. Accurate Pricing
With a clear understanding of your home’s condition, you can price it more accurately, avoiding overpricing or underpricing.
2. Builds Buyer Confidence
Buyers are more likely to make offers on homes that have already been inspected. This transparency can lead to faster decisions and fewer delays.
3. Faster Closing
Addressing repairs upfront leads to fewer negotiations and potential delays during closing, making the process quicker and smoother.
4. Avoid Price Negotiations
If buyers discover issues during their own inspection, they may ask for price reductions or repairs. A pre-listing inspection helps you avoid these surprises.
5. Improved Negotiation Leverage
Fixing issues ahead of time can give you more power in negotiations, helping you maintain your asking price.
6. Reduces Deal Risks
A pre-inspection minimizes the chances of a sale falling through due to unexpected issues discovered later on.
What’s Covered in a Pre-Listing Inspection?
A pre-listing inspection typically checks:
- Structural Integrity: Foundation, roof, and walls
- Plumbing & Electrical: Functionality and safety
- HVAC & Appliances: Condition and performance
- Exterior/Interior: Windows, doors, and overall condition
Should You Get One?
While the cost of a pre-listing inspection (around $300-$600) can be an investment, the benefits of setting the right price, avoiding surprises, and closing quickly often outweigh the expense. It’s particularly useful in a competitive market, but may not be necessary if your home is newly renovated or in a hot seller’s market.
Conclusion
A pre-listing inspection can provide significant advantages, helping you sell your home faster, with fewer complications, and at a fair price. If you’re considering selling, a pre-listing inspection could be a smart move to streamline the process and increase your chances of success.