by Katherine Soditus | Jan 7, 2026 | Uncategorized
In the United States, credit scores play a central role in whether a borrower is approved for a loan, how much they pay in interest, and what terms they receive. Whether you are applying for a mortgage, auto loan, personal loan, student loan, or a credit card, lenders use credit scores as a key indicator of your creditworthiness.
What a Credit Score Represents
A credit score is a three‑digit number that reflects your history of borrowing and repaying money. It is calculated using information from your credit reports, including payment history, amounts owed, length of credit history, types of credit used, and new credit inquiries. The most commonly used scores range from around 300 to 850, with higher scores showing stronger credit management.
Loan Approval Decisions
Lenders use credit scores to assess risk. A higher credit score signals that you are more likely to repay your debts on time, so lenders are more willing to approve your loan application. Lower scores suggest higher risk, which can lead to denials or stricter conditions.
For many loans, lenders have minimum score requirements. For example, conventional mortgages might require a higher credit score than some government‑backed loans, while auto lenders may approve higher‑risk borrowers but at higher costs.
Interest Rates and Loan Terms
Credit scores do more than determine approval. They influence the interest rates, fees, and terms of your loan. Borrowers with higher scores typically receive:
-
Lower interest rates, meaning lower monthly payments and less paid in interest over the life of the loan
-
Better loan terms, such as longer repayment periods or smaller down payment requirements
-
Greater borrowing options, including access to premium loan products
Conversely, higher‑risk borrowers with lower scores may be offered loans with higher interest rates or require larger down payments and more restrictive terms.
Types of Loans Affected
Credit scores impact nearly every type of consumer credit:
-
Mortgages: Higher scores help secure the most competitive mortgage rates and avoid costly private mortgage insurance (PMI) in some cases.
-
Auto Loans: Better scores often qualify buyers for lower rates and flexible terms.
-
Personal Loans: Lenders use credit scores heavily here; unsecured personal loans may be unavailable to those with poor scores.
-
Credit Cards: Scores influence approval, credit limits, and card rewards opportunities.
-
Student Loans: While federal student loans do not require credit scores, private student loans do, affecting approval and rates.
How to Improve Your Credit Score
Improving your credit score can significantly impact your borrowing costs and eligibility:
-
Pay bills on time: Payment history is one of the most important score factors.
-
Reduce debt: Lowering credit card balances relative to limits can boost your score.
-
Avoid unnecessary inquiries: Applying for too many new accounts in a short time can lower your score.
-
Build a healthy credit mix: Having a combination of different credit types can help if managed responsibly.
Final Thought
Your credit score matters. It affects whether you qualify for a loan, how much you pay, and what borrowing opportunities are available to you. Understanding how credit scores influence loan approval nationwide empowers consumers to manage their financial profiles and pursue better borrowing outcomes. By building and maintaining strong credit, borrowers can unlock more favorable loan options and save money over time.
by Katherine Soditus | Sep 8, 2025 | Uncategorized
Real estate investing isn’t just about cash flow and appreciation — one of the most powerful advantages is how favorable the U.S. tax code can be for investors. Understanding these tax benefits can dramatically increase your returns and help you build long-term wealth.
Here are the top tax benefits real estate investors in the USA can take advantage of:
1. Depreciation Deduction
One of the biggest tax advantages is depreciation, which allows you to deduct a portion of the property’s value each year — even if the property is appreciating in market value.
Example: If your rental property (excluding land) is worth $275,000, you can deduct $10,000 per year in depreciation — even if the property is gaining value.
2. Deductible Expenses
Many of the costs involved in owning and managing an investment property are tax-deductible, including:
These deductions can significantly reduce your taxable rental income.
3. 1031 Exchange (Like-Kind Exchange)
Section 1031 of the IRS code allows you to defer capital gains taxes when you sell an investment property and reinvest the proceeds into a “like-kind” property.
This strategy is widely used by investors looking to scale or upgrade their portfolios without a big tax bill.
4. Capital Improvements vs. Repairs
While routine repairs are deductible in the year they’re made, capital improvements (like a new roof or a kitchen remodel) can increase your property’s basis and reduce capital gains when you sell.
Tip: Be strategic about categorizing your upgrades — work with a tax advisor to ensure proper treatment.
5. Pass-Through Deduction (Section 199A)
If you own your properties through a pass-through entity (LLC, S-Corp, or even as a sole proprietor), you may qualify for a 20% deduction on qualified business income under the Tax Cuts and Jobs Act.
6. Offsetting Other Income with Passive Losses
Real estate generates passive income, and the IRS allows you to use passive losses (from depreciation or other deductions) to offset passive income from other sources.
7. Step-Up in Basis (for Estate Planning)
When you pass real estate down to your heirs, they receive a step-up in basis — meaning the property’s value is adjusted to its current market value at the time of your death.
This is a powerful wealth preservation strategy for long-term investors.
8. Opportunity Zones
Investing in Qualified Opportunity Zones allows investors to:
-
Defer capital gains taxes
-
Reduce tax liability on gains held for a certain period
-
Potentially eliminate taxes on new gains if the investment is held for 10+ years
These zones are part of a federal initiative to encourage investment in underdeveloped areas.
Final Thoughts
The U.S. tax code is incredibly friendly to real estate investors — if you know how to take advantage of it.
by Katherine Soditus | Aug 25, 2025 | Uncategorized
The red-hot real estate market of 2020–2022 left many buyers bracing for bidding wars, waived inspections, and paying well over asking price. But as the housing landscape continues to shift in 2025, many are wondering: Should you still expect a bidding war today?
The short answer? It depends.
Let’s break down what’s driving buyer competition in today’s market—and whether bidding wars are still something to prepare for.
Location Is Still Everything
One of the biggest factors in whether you’ll face multiple offers is where you’re buying or selling.
In high-demand urban and suburban markets—like parts of California, Texas, Florida, and the Northeast—competition remains strong, especially for homes in good condition and well-rated school districts. These areas continue to attract buyers despite higher interest rates, thanks to limited inventory and job growth.
However, in more balanced or cooling markets, bidding wars are less common. Many homes are selling closer to asking price, and buyers often have a bit more time and negotiation room.
Market Conditions in 2025: What’s Changed?
Several broader economic trends are reshaping the real estate playing field:
-
Mortgage rates remain elevated, hovering around 6–7%, which has cooled some buyer enthusiasm.
-
Inventory is gradually increasing, though it’s still below historical norms. That means more choices for buyers—but not enough to shift power fully away from sellers.
-
Buyer demand is down from pandemic highs, but still relatively strong—particularly in the affordable home segment.
The Result?
We’re not in the frenzy of 2021 anymore, but bidding wars haven’t vanished entirely. They’re just more selective.
What Types of Homes Still Attract Bidding Wars?
While not every listing sparks a bidding war, certain types of homes still draw fierce interest:
Move-in ready homes
Properties under the local median price
Homes in top-rated school districts
Updated or newly renovated homes
Locations with a strong job market and limited housing supply
On the other hand, higher-priced homes, fixer-uppers, or homes in areas with rising inventory may sit longer and sell with price adjustments.
Advice for Buyers
If you’re entering the market, here’s how to prepare:
-
Get pre-approved before you shop. This shows sellers you’re serious.
-
Know your limits. Decide how much over asking (if any) you’re willing to offer.
-
Be ready to act fast in hot markets—but don’t rush into overpaying.
-
Work with a knowledgeable agent who understands local trends.
Advice for Sellers
Thinking of listing your home? You may still be able to generate multiple offers—if you:
-
Price it correctly from day one
-
Stage and prepare your home for showings
-
Market strategically with strong online visibility and professional photos
Even in a slower market, a well-prepared home at the right price can still spark a bidding war.
Final Thoughts: Expect Competition—But Don’t Panic
Today’s market is more balanced than it was at the height of the pandemic boom, but it’s still competitive—especially in sought-after locations and price points. Bidding wars still happen, but they’re no longer the norm across the board.
So should you expect a bidding war?
If you’re buying in a hot area or under the median price yes, it’s possible.
If you’re shopping at a higher price point or in a more balanced market—not likely, but still possible depending on the home.
by Katherine Soditus | Jul 17, 2025 | Uncategorized
Investing in real estate can be a powerful way to build long-term wealth, generate passive income, and diversify your financial portfolio. However, financing investment properties is a different ballgame than purchasing a primary residence—and missteps can quickly turn a promising deal into a costly mistake.
To help you succeed, here are the top mistakes investors make when financing investment properties—and how to avoid them.
1. Not Understanding Loan Options
Many first-time investors assume that getting a loan for an investment property works the same way as buying a home to live in. It doesn’t. Investment property loans often come with higher interest rates, stricter qualification criteria, and larger down payment requirements.
What to do instead:
Explore various loan types such as:
-
Conventional loans for long-term rentals
-
Hard money loans for flips or short-term deals
-
DSCR (Debt Service Coverage Ratio) loans for income-based financing
-
Portfolio loans from lenders who keep loans in-house
Talk to lenders who specialize in investment properties, and choose the right product based on your strategy.
2. Underestimating the True Costs
Many investors budget for the purchase price and monthly mortgage payment—but overlook expenses like repairs, property taxes, insurance, vacancies, and maintenance. This can destroy cash flow and delay profits.
What to do instead:
Build a comprehensive budget that includes:
-
Closing costs
-
Capital expenditures (roof, HVAC, etc.)
-
Property management fees
-
Utilities (if paid by the landlord)
-
Reserves for unexpected costs
Being overly conservative is better than being surprised.
3. Overleveraging
It’s tempting to maximize your buying power using leverage, especially when markets are rising. But taking on too much debt without a financial cushion can backfire fast in a downturn, or during prolonged vacancies.
What to do instead:
Use leverage responsibly. Keep an eye on your debt-to-income (DTI) ratio and loan-to-value (LTV). Run stress tests: what happens if your rent drops by 20% or if interest rates rise by 2%? Make sure you can survive a rough patch.
4. Poor Credit Planning
Your credit score significantly impacts your financing terms. A lower score can mean higher interest rates, tougher conditions, or outright denial.
What to do instead:
-
Check your credit report well in advance
-
Dispute any errors
-
Pay down revolving credit
-
Avoid new credit inquiries before applying
Even a 20–30 point improvement in your score can save thousands over the life of a loan.
5. Not Getting Pre-Approved
Investors often fall in love with a property, then scramble for financing—only to learn they can’t qualify, or the timeline doesn’t work.
What to do instead:
Get pre-approved with a lender who understands investment properties. This not only saves time but also strengthens your offers when negotiating with sellers.
6. Ignoring the Property’s Cash Flow
Some investors buy based on appreciation potential, ignoring the fact that the property may not generate positive monthly cash flow. This speculative approach is risky.
What to do instead:
Evaluate deals based on current and realistic rental income using:
Make sure the numbers make sense today—not just in a “best-case” future scenario.
7. Failing to Plan for Scaling
Early financing decisions can make or break your ability to grow your portfolio. If you use up your personal borrowing capacity or choose loans that can’t be refinanced, you may hit a ceiling fast.
What to do instead:
Structure your investments with scaling in mind:
-
Use LLCs for ownership and liability protection
-
Consider commercial financing after 4+ properties
-
Keep personal DTI low if planning to use conventional loans
8. Skipping Professional Help
Financing investment properties involves legal, financial, and tax considerations. DIY-ing everything or relying on informal advice can lead to costly mistakes.
What to do instead:
Build a professional team that includes:
-
A mortgage broker familiar with investment lending
-
A CPA who understands real estate tax strategy
-
A real estate attorney (especially for multi-units or partnerships)
-
A property manager to help you project realistic numbers
Good advice pays for itself in avoided headaches.
:white_check_mark: Final Thoughts
Financing investment properties is not just about getting a loan—it’s about making smart, long-term financial decisions that support your goals. By avoiding these common pitfalls and working with the right professionals, you can build a profitable and scalable real estate portfolio.
by Katherine Soditus | Jul 7, 2025 | Uncategorized
If you’re house hunting this summer, you’ve probably been asking yourself:
“What’s up with mortgage rates lately?”
And it’s a fair question — rates in 2025 have been keeping buyers, sellers, and real estate pros on their toes.
After years of fluctuation, from rock-bottom lows to steep hikes, the mortgage market is still settling into a new rhythm. So if you’re trying to make sense of the headlines (or just wondering what this all means for your buying plans), you’re not alone.
Let’s break down what’s actually going on with mortgage rates in July 2025, what’s influencing them, and what you can do as a smart, informed homebuyer in today’s market.
So, Where Are Rates Right Now?
As of July 2025, the average 30-year fixed mortgage rate is sitting around 6.5% to 6.9%, depending on the lender, your credit score, and down payment. That’s a little lower than the peak we saw in late 2023 and early 2024 (when rates topped 7%), but still higher than what many buyers were used to back in the ultra-low pandemic years.
If you’re eyeing a 15-year fixed mortgage, those rates are slightly lower — often in the 5.8% to 6.2% range. Adjustable-rate mortgages (ARMs) are back in the spotlight too, with some offering lower initial rates for buyers willing to take on a bit more risk.
Bottom line? Rates aren’t “high,” they’re normalizing — and that’s not a bad thing.
What’s Driving Mortgage Rates Right Now?
Mortgage rates are influenced by a mix of economic signals. Here’s what’s playing a role this summer:
-
Inflation is still a factor. While it’s cooled from the spikes we saw in 2022 and 2023, it’s not entirely under control. The Fed is still keeping a close eye and hasn’t ruled out additional policy tweaks.
-
The Federal Reserve hasn’t made any major rate hikes lately, but they’re also not cutting rates just yet. They’re in a “wait-and-see” mode, trying to balance inflation without stalling economic growth.
-
Employment numbers and consumer spending are holding steady, which tells lenders that borrowers can generally handle slightly higher interest payments — meaning no urgency to slash rates.
-
Global economic trends — including ongoing supply chain recovery and international conflict — also affect investor behavior and bond markets, which indirectly impact mortgage rates.
Should You Wait for Lower Rates?
Here’s the honest truth: no one knows exactly when (or if) rates will drop significantly.
Some experts predict modest rate decreases in late 2025 or early 2026, but nothing like the 3% rates we saw in 2020–2021. If you’re waiting for those days to come back… don’t hold your breath.
Instead of trying to “time the market,” ask yourself this:
“Can I afford a home I love at today’s rates — and would I still love that home five years from now?”
If the answer is yes, it may make sense to move forward now. Many buyers opt to “marry the house and date the rate” — meaning you buy the home you want, and refinance later if rates drop.
Pro Tip: Rate Hacks for 2025 Buyers
Even with rates where they are, there are smart strategies you can use to get the best deal possible:
-
Boost your credit score. Even a 20-point jump can save you thousands in interest over time.
-
Consider a rate buydown. Some sellers or builders offer to “buy down” your rate for the first few years — especially in a slower market.
-
Shop around. Don’t settle for the first lender you talk to. Different lenders offer different programs, especially for first-time buyers.
-
Look into loan programs. FHA, VA, USDA, and state/local first-time buyer programs may offer lower rates, reduced fees, or down payment assistance.
-
Ask your lender about refinancing options. Knowing your future options gives peace of mind when rates eventually shift.
What Does This Mean for You?
Mortgage rates are just one piece of the puzzle — and while they matter, they shouldn’t be the only thing driving your decision. The right time to buy is when you’re financially ready, have a stable income, and are excited about putting down roots.
And remember: millions of people bought homes when rates were higher than this and still built equity, stability, and wealth over time. You can too — especially if you go in with the right strategy and support.
Ready to Talk Numbers?
If you’re feeling unsure about your buying power or what kind of home fits your monthly comfort zone, I’d love to help you run the numbers. Whether you’re buying in the next few weeks or just exploring your options, we can chat about budget, rates, and what makes sense for you.
Mortgage rates don’t have to be scary — not when you’ve got good information and a great team behind you.
Let’s figure it out together.
by Katherine Soditus | Mar 3, 2025 | Featured, Inventory, Sellers
Many homeowners hesitate to sell their homes due to unanswered questions and doubts. However, these concerns are often based on misconceptions rather than facts. If you’re unsure about whether it’s the right time to sell, talking to a real estate agent could clear up any uncertainties. You might find that your worries aren’t as big of a hurdle as you thought.
If you’re feeling uncertain about moving, it’s time to get the real answers. Here’s a look at some common questions homeowners have about selling their homes and the data that answers them.
- Is It a Good Time to Sell My Home?
One of the biggest concerns for homeowners is the fear of selling and then dealing with higher mortgage rates when buying a new home. While this concern is valid, it might not be as much of a barrier as you think.
The good news is that home values have likely increased significantly since you bought your home. According to Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), the average homeowner has gained $147,000 in housing wealth over the past five years. This means that selling your home could provide you with the financial resources to afford your next move, even if mortgage rates are higher than before.
- Will I Be Able to Find a Home I Like After Selling?
Many buyers have struggled to find a home in recent years due to low inventory and high demand. However, the market is now much more favorable for those looking to purchase a new home.
According to Realtor.com, housing inventory has increased by nearly 25% compared to the previous year. Although inventory is still below pre-pandemic levels, this increase is a positive sign for homebuyers. Experts predict that housing inventory will grow another 10-15% this year, giving you more options when searching for your next home. This means you’re more likely to find a property you love in today’s market.
- Are Buyers Still Active in the Market?
If you’re wondering whether buyers are still purchasing homes, you’ll be happy to know that the market is still active, despite higher mortgage rates and home prices.
According to the National Association of Realtors (NAR), approximately 4.24 million homes were sold last year, even though the market wasn’t as competitive as in previous years. To put this into perspective, that’s about 11,616 homes sold every day, or 484 homes sold every hour. In fact, homes are selling every minute of the day. This means that even as you read this article, buyers are actively looking for homes, including properties like yours.
Bottom Line: Now Might Be the Right Time to Sell Your Home
If you’re considering selling your home but feel uncertain, now is the time to connect with a real estate agent. They can help you navigate the current market and answer any questions you have about the process. With home values on the rise, an increase in inventory, and a market still full of buyers, the timing could be right to sell your home and make a move.
Don’t let uncertainty hold you back. Get the answers you deserve and take the next step in your homeownership journey today.
by Katherine Soditus | Feb 26, 2025 | Residential | Active

$279,000
Active
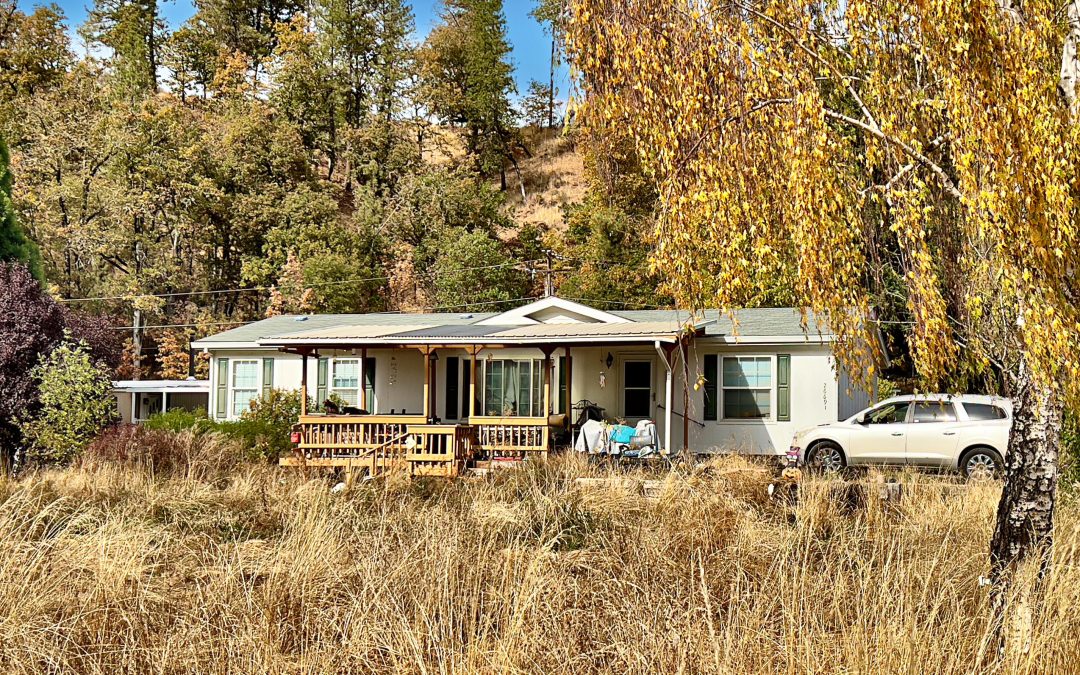
ACREAGE, ”SHOP” w/ADU POTENTIAL, CARPORT w/RV METER, WOW! Spacious 3bd/2ba manufactured home with covered porch on mostly level acreage. Split floor plan offers a primary suite with oversized soaking tub, dual vanities and a separate shower. Vaulted living spaces with ceiling fans; laundry room/mudroom. The wood framed workshop with glass slider may potentially convert to an ADU or additional finished area (inquire with county; workshop was remodeled from a previous ”old house”) The upper detached metal carport has an RV meter and the lower carport is adjacent to a shed; there’s ample room for storage and plenty of parking for RV, boat, trailers & toys. Property features multiple sheds/storage outbuildings, a fire-pit, even an older hot tub. Property is partially fenced. New 2000 gallon holding tank and pump just installed 10/2021, new well pump & pipeline in 2022. This home has ”short sale conditions” and is subject to bank approval; inquire with listing agent for details.
by Katherine Soditus | Feb 25, 2025 | Sellers
2025 could be the year you’ve been waiting for! According to a recent NerdWallet survey, 15% of people plan to buy a home this year — a record high for this survey. Whether you’re considering selling or just curious about the market, this increase in buyer intent signals that 2025 is shaping up to be a great year for sellers.
Ready to see why now might be your golden opportunity to sell? Let’s dive in!
Why Buyer Demand is Booming in 2025
Over the past few years, the percentage of buyers planning to purchase a home has hovered between 9-11%. But this year? We’re seeing a significant jump to 15% — signaling that more buyers are gearing up to take the plunge.
What does this mean for you as a seller? Pent-up demand is finally being released, and buyers are more motivated than ever. While we may not see the huge waves of activity we saw in years past, there will definitely be more buyers in the market this year, and many are eyeing the peak spring season to make a move.
What’s Fueling the Surge in Buyers?
So, why the sudden uptick in buyer activity? Here are a few key reasons:
- Buyer Confidence is Back: After a few years of uncertainty, many buyers are feeling ready to move forward and make that big purchase.
- Financial Prep: Buyers have had time to save for a down payment and are now in a stronger financial position to buy.
- A Growing Sense of Urgency: Some buyers who’ve been waiting are no longer willing to sit on the sidelines. They’re jumping back in this year!
And guess what? 54% of potential buyers have already started looking at homes online. That’s right — the buyers are out there, and they’re eager to find their next home.
Why 2025 is a Prime Time to Sell Your Home
With more motivated buyers in the market, it’s the perfect time for sellers to list their homes. But how can you ensure your home stands out from the competition? Here’s how:
- Partner with the Right Agent: A skilled real estate agent can help you price your home competitively, market it effectively, and negotiate the best deal.
- Prep Your Home for Sale: A little TLC goes a long way! Make sure your home is in top shape — from simple upgrades to boosting curb appeal — to wow potential buyers.
- List Before the Rush: Spring is when the market really heats up. Listing your home a bit ahead of time can ensure it’s ready when the majority of buyers are actively searching.
The Secret to Getting Your Home Noticed
Now, let’s talk about the wow factor — what will buyers love most about your home? Whether it’s that spacious kitchen, the beautiful backyard, or a freshly renovated bathroom, highlight what makes your home unique in your listing. When buyers are scrolling through countless listings online, you want yours to catch their eye instantly.
Maximize Your Home’s Appeal with These Tips
- Stage Your Home: A well-staged home helps buyers visualize themselves living there. It’s worth investing time in making your home feel inviting and spacious.
- Price It Right: Overpricing can turn buyers away, but a strategically priced home can spark bidding wars.
- Professional Photos Are Key: Buyers want to see your home in its best light — literally! High-quality photos make your listing stand out online.
- Highlight Your Home’s Best Features: Whether it’s the view, the location, or custom features, make sure these details are front and center in your listing.
Why Spring is the Best Time to Sell Your Home
Spring is traditionally the busiest homebuying season, and with more buyers entering the market, it’s the time to strike while the iron’s hot. So, if you’re thinking about selling, spring could be your window of opportunity to showcase your home and attract serious buyers.
Ready to Sell? Here’s What You Can Do Next:
- Connect with an Expert Agent: The right agent will know the ins and outs of the market and help you navigate the process smoothly.
- Get Your Home Market-Ready: Take the time to make any necessary repairs or improvements and get your home looking its best.
- List Early: Beat the spring rush and get your home on the market as soon as possible to capture the most attention.
The Bottom Line: 2025 is Your Year to Sell!
With increased buyer interest and spring around the corner, 2025 is shaping up to be a fantastic year for sellers. With the right strategy, your home could be one of the most sought-after properties in your area. Don’t wait any longer — connect with a trusted real estate agent and start preparing your home for sale today!
Want to make the most of this year’s real estate market? Let’s talk! Reach out today to get your home ready for sale and make sure it’s front and center when buyers start looking.
by Katherine Soditus | Feb 25, 2025 | Land | Active

$129,000
Active
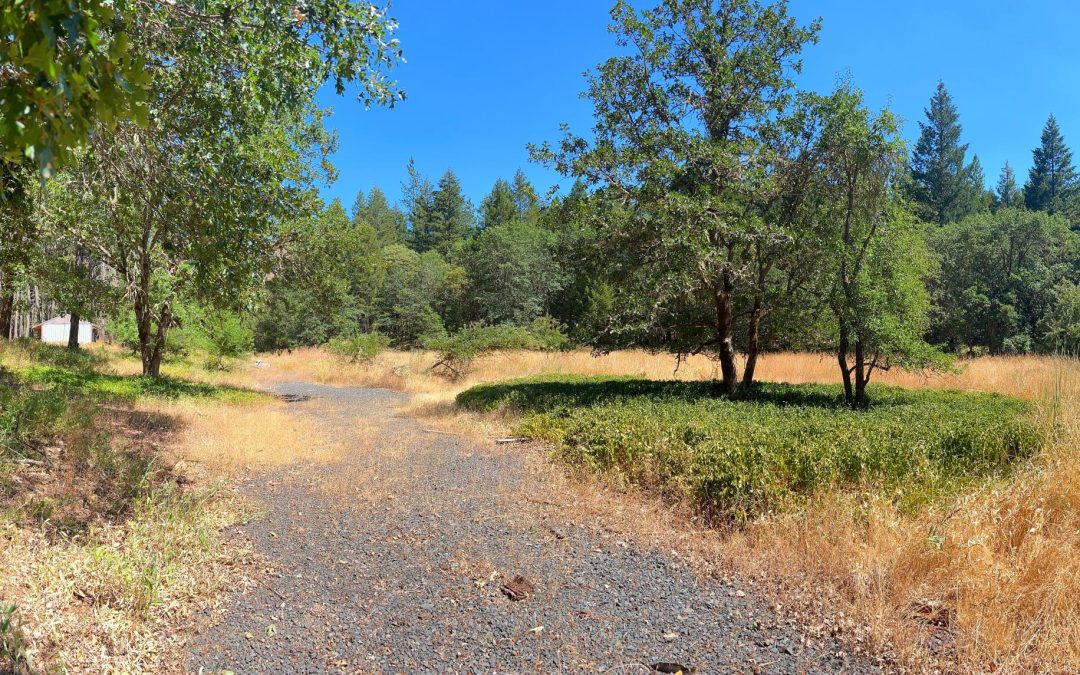
Seize this remarkable opportunity to own a stunning 7.83-acre lot, perfectly located just 1/3 mile from the beautiful Lake Selmac and the resort community – only 20 miles from Grants Pass! This property offers a captivating blend of flat, picturesque fields and gently rolling wooded hills, cleared of underbrush, making it an ideal canvas for your dream home, garden, or small farm. With a well already in place and a 16×16 shed, this parcel is ready for your vision. Enjoy the serenity of a seasonal creek that runs through the landscape and the abundance of wildlife that calls this area home. The NE corner of the property abuts the SW corner of BLM land, providing even more privacy and natural beauty. Don’t miss your chance to create your own oasis in this sought-after location. With neighboring properties boasting of several natural springs and ample flat space for gardening or livestock, the potential here is limitless. Act quickly—contact me today to explore this incredible property!
by Katherine Soditus | Feb 17, 2025 | Agent Value, Sellers
Selling a home is a major financial decision, and while the real estate market offers opportunities, it also comes with challenges. In 2025, many home sellers unknowingly make mistakes that can reduce their chances of getting the best deal. Whether you’re planning to sell soon or just want to prepare for the future, here are 3 critical mistakes to avoid when selling your home.
1. Overpricing Your Home
One of the most common mistakes home sellers make is overpricing their property. While it may seem like a good idea to set a high asking price and leave room for negotiation, overpricing can backfire.
Why Overpricing Hurts Your Sale:
- Buyer Perception: If a home stays on the market too long, potential buyers might assume there’s something wrong with it.
- Price Reductions: If your home doesn’t sell quickly, you may have to reduce the price, which can make it seem less desirable.
- Fewer Offers: A high asking price can deter potential buyers, leading to fewer offers and ultimately a lower final sale price.
Tip: Work with a real estate agent who understands your local market. A competitive, realistic price can attract more buyers, which may lead to a higher sale price in the long run.
2. Neglecting Repairs and Updates
Skipping essential repairs and updates is a costly mistake many home sellers make. Buyers typically prefer homes that are move-in ready, and visible damage or outdated features can deter them, even if the price seems right.
What to Fix Before Listing:
- Minor Repairs: Fix small issues like leaky faucets, cracked walls, or faulty light switches to give the impression of a well-maintained home.
- Update Outdated Features: Consider updating your kitchen or bathroom with affordable renovations that give your home a modern feel.
- Boost Curb Appeal: First impressions matter. Clean up your landscaping, paint the front door, and maintain walkways to make your home inviting from the outside.
Tip: Even if you can’t afford major renovations, small improvements can help your home stand out and potentially fetch a higher price.
3. Not Preparing for Showings
How your home looks during showings can determine if it sells quickly — or at all. Many sellers underestimate the importance of staging and preparing their property for potential buyers.
Steps to Prepare Your Home:
- Clean Thoroughly: A clean home signals to buyers that it’s well-cared for and ready to move into.
- Declutter: Remove personal items, unnecessary furniture, and anything that makes the space feel cramped. Let the home’s potential shine through.
- Stage Your Home: Simple staging, like rearranging furniture or adding decorative touches, can help buyers imagine living in the space.
- Professional Photography: High-quality photos for online listings are a must. Great photos can attract more buyers and lead to more showings.
Tip: Presenting a well-staged, clean, and tidy home will increase the chances of a quick sale at the right price.
Conclusion: How to Sell Your Home Successfully in 2025
To sell your home in 2025 successfully, avoid these three mistakes:
- Price your home realistically based on current market conditions.
- Make necessary repairs and updates to ensure your home is move-in ready.
- Prepare for showings by decluttering, cleaning, and staging your property.
By following these simple steps, you’ll improve your chances of a quick and profitable sale. Partnering with an experienced real estate agent can also guide you through the process and ensure your home is market-ready.